India Overhauls UPI: New Merchant Fees Explained
The era of entirely free instant digital payments in India is drawing to a close. The National Payments Corporation of India (NPCI) has announced a…
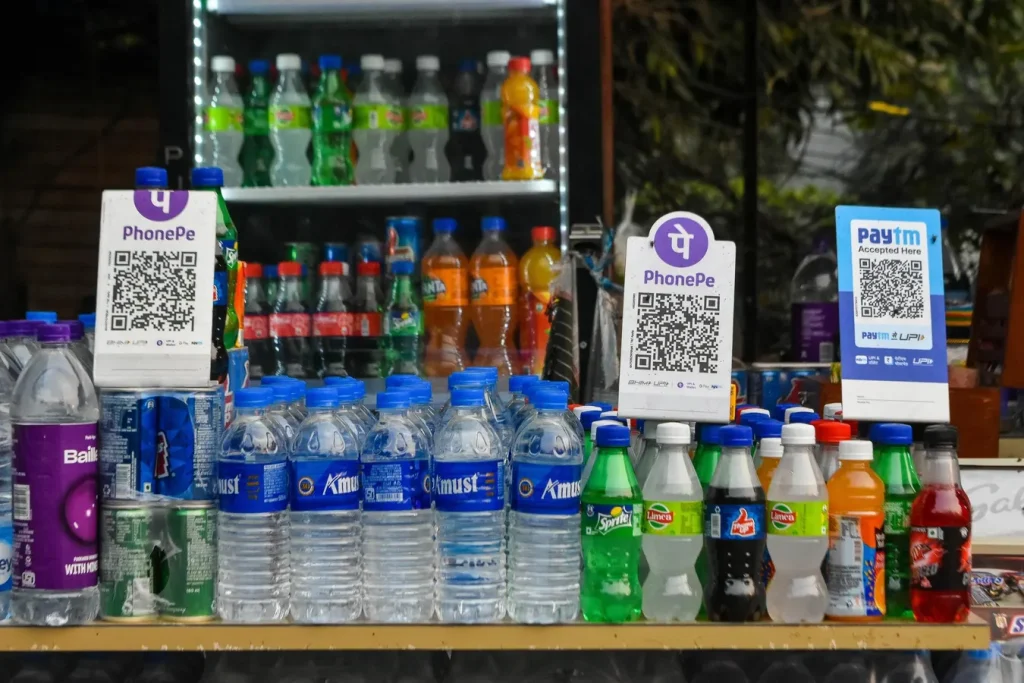
Featured image for news article
The era of entirely free instant digital payments in India is drawing to a close. The National Payments Corporation of India (NPCI) has announced a significant policy shift that will introduce new charges for specific merchant transactions made through the Unified Payments Interface (UPI). Starting October 15, businesses will face a 0.4 percent levy on transactions exceeding 2,000 rupees ($21).
Since its inception a decade ago, UPI has revolutionized India’s financial landscape. By offering a frictionless, cost-free method for transferring funds, it has become the backbone of the nation’s economy, bridging the gap between small street vendors and massive corporate retail chains. However, this transition toward a fee-based model signals a move to shift infrastructure maintenance costs away from banks and fintech firms.
The Mechanics of the New Levy
The updated fee structure introduces a tiered system for commercial payments. Transactions above the 2,000-rupee threshold will be subject to a 0.4 percent charge, which is capped at 300 rupees per transaction. Conversely, all person-to-person transfers will continue to be processed free of charge, ensuring that casual users remain unaffected by the policy change.
Furthermore, the government has implemented a flat fee of five rupees for specific services. This includes payments made at fuel stations, railway ticket bookings, and telecom bill settlements. While the government categorizes this as a Merchant Discount Rate (MDR), the move has ignited a fierce debate regarding who should ultimately bear the burden of sustaining digital infrastructure.
Political and Economic Ripples
The decision has sparked a political firestorm. Opposition leaders have criticized Prime Minister Narendra Modi’s government, alleging that these costs are being passed down to merchants under pressure from international entities. Critics argue that such levies could discourage small businesses from participating in the digital ecosystem, potentially slowing the momentum of India’s cashless transition.
While the government has explicitly barred merchants from offloading these costs onto consumers, the ground reality suggests a different trend. Business owners are already finding ways to circumvent these restrictions to protect their thin profit margins. For many, the math is simple and unavoidable.
“If the government charges us, we increase costs for customers. It’s simple maths,” said Vikas Mahto, a grocery store operator in the National Capital Region.
Mahto has already begun implementing a five-rupee surcharge on all digital transactions exceeding 1,000 rupees. His approach highlights a growing tension between national policy and the practical realities of small-scale commerce. As the October 15 deadline approaches, the broader impact of these charges on merchant adoption remains a subject of intense concern for economic analysts.
The sheer scale of UPI makes this development globally significant. With record-breaking transaction volumes, the system remains a model for digital payment interfaces worldwide. Whether this new fee structure sustains the network’s long-term growth or alienates its base of small-scale merchants is a question that will define the next chapter of India’s digital journey.